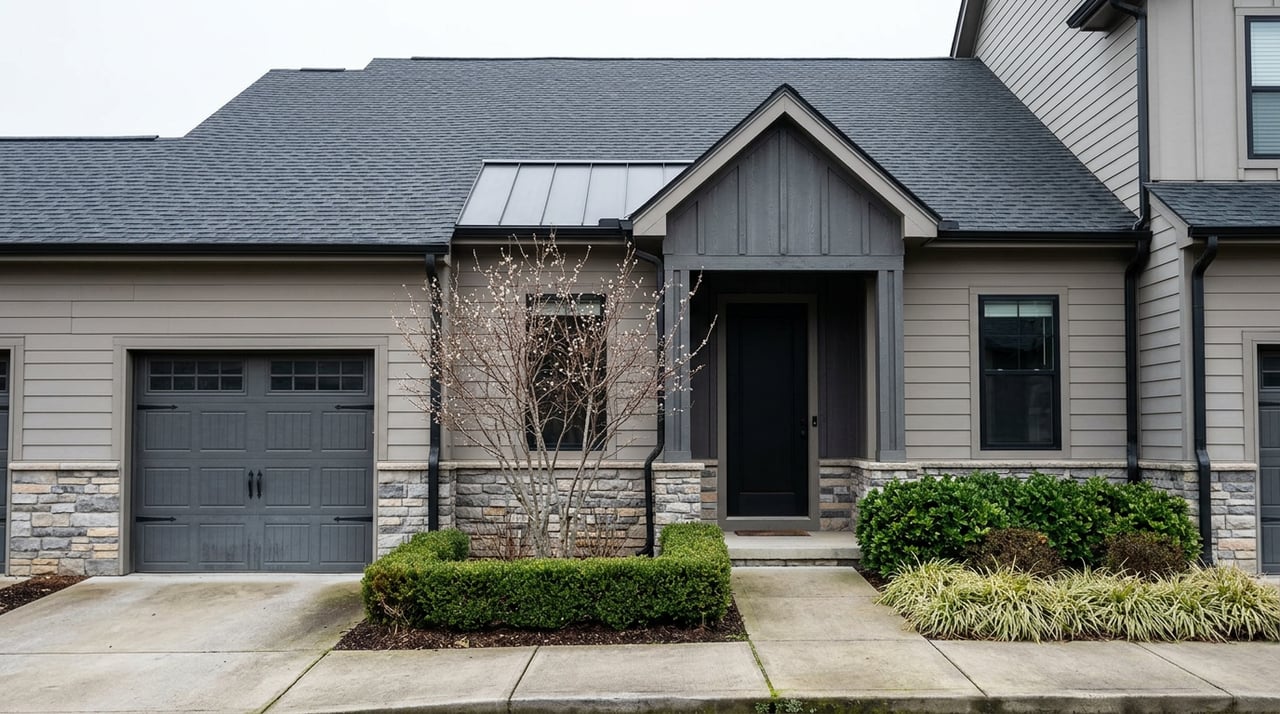
Scroll through the new-construction listings at Hudson Ridge, the townhome community going up off Bradford Drive in Red Lion, and you'll see the usual mid-market checklist: granite countertops, an island kitchen, stainless appliances, a $25 monthly HOA fee that covers ground maintenance. Then, sitting right next to the floor plan and the builder's $5,000 closing-cost incentive, you'll see three words that don't seem to belong there: USDA eligible.
That label is supposed to signal a rural loan program built for farmhouses and unincorporated back roads. Hudson Ridge is a 320-plus unit subdivision with a dog park, a resident manager, and quick access to Route 24, Route 74, and I-83. So how does a three-story townhome with 9-foot ceilings end up qualifying for the same financing tool the federal government designed to house families outside the reach of a metropolitan mortgage market?
The answer has almost nothing to do with how rural Hudson Ridge feels. It has everything to do with two separate government tests that were never designed to measure that in the first place.
Two Tests, Not One Feeling
USDA Rural Development financing runs on two independent gates, and a property or a buyer can clear one while failing the other entirely.
- The location test. USDA Rural Development classifies an area as eligible if its population sits at 20,000 or below and it falls outside a metropolitan statistical area, or up to 35,000 if the area was previously classified rural and grandfathered forward. Nothing in that rule asks whether the community has a highway interchange nearby, whether the homes have granite countertops, or whether a commuter can reach Baltimore or Washington in under two hours. It's a population count and an MSA boundary line, full stop.
- The income test. Separately, USDA caps how much a household can earn and still qualify, and that ceiling is set by loan program and updated on its own schedule.
A buyer needs to clear both. A property that sits in an eligible zip code doesn't help a household that earns too much. A qualifying income doesn't help a buyer looking at a home outside the boundary. The two tests run on completely different logic, and treating "USDA eligible" as a single stamp of approval is where most of the confusion starts.
That population-and-MSA rule is also why the label survives contact with a place like Red Lion. York County's population and its distance from Baltimore and Harrisburg don't disqualify individual municipalities the way you'd expect, because the classification runs off local population figures and metro boundary lines, not felt commute time or how developed the surrounding roads look.
What Hudson Ridge Actually Is
Hudson Ridge is being built by Burkentine and Sons Builders, and construction on the community began in 2023 with a plan for 320 townhomes for sale alongside 134 for rent, all within the Dallastown Area School District. That last detail matters on its own: the community carries a Red Lion mailing address, but a child living there attends Dallastown schools, not Red Lion's. It's the kind of mismatch between what's printed on an envelope and which municipal or school lines actually apply that trips up buyers who assume an address settles the question.
By this summer, the builder had moved into Phase 3, with floor plans running roughly 1,700 to 1,900 square feet and base pricing landing in the high $270,000s to mid $320,000s depending on the unit and lot. That price point is worth holding onto, because it's about to matter more than the eligibility label itself.
The Income Ceiling Depends On Which USDA Loan You Mean
This is where the research on Red Lion got genuinely interesting, because two credible sources gave two different income ceilings for York County, and the gap isn't a mistake. It's a sign of two different USDA programs.
USDA runs a Guaranteed Loan program, originated through private lenders and backed by the federal government, and a separate Direct Loan program, funded and serviced by USDA itself for lower-income households who can't get financing anywhere else. Each program sets its own income ceiling, and a York County-specific lending directory from USDAProperties.com that quotes $94,500 for a one-to-four person household. The number that applies to the vast majority of Red Lion buyers working with a bank or credit union is the Guaranteed Loan ceiling, and according to Rural Home Check's FY2026 table, effective July 13, 2026, that moderate-income limit sits at $122,800 for a one-to-four person household and $162,100 for a household of five to eight in most counties.
| Income-limit source or program | Household of 1 to 4 | Household of 5 to 8 |
|---|---|---|
| York County lending-directory figure | around $94,500 | around $124,750 |
| USDA Guaranteed Loan (moderate-income, most counties, effective July 2026) | $122,800 | $162,100 |
That's roughly a $28,000 swing on the smaller household size, depending entirely on which program a lender is quoting. If you've seen a lower number attached to York County somewhere and assumed you were priced out, it's worth asking your loan officer which program that figure actually describes before you rule anything out.
What This Means If You're Comparing Red Lion Options
Here's the part that actually affects a buying decision. USDA financing doesn't remove the price-to-income math that governs every mortgage. Loan-tracking data on USDA-backed lending in York County shows the typical borrower carried an average loan balance of about $147,827 as of mid-2026, financed a home appraised around $148,169, and bought roughly 1,431 square feet, and 84 percent of those borrowers were purchasing their first home.
Hudson Ridge's base pricing runs meaningfully above that typical USDA-financed home value in the county. That doesn't disqualify the community. It means the "eligible" label tells you the location and the loan structure are available, not that the specific unit and price point automatically fit every USDA-qualified household's debt-to-income ratio. Two buyers can both clear the location and income tests and still land in very different places on whether a particular Hudson Ridge floor plan actually pencils out against their income once the loan officer runs the full underwriting math.
This is the comparison worth having before you fall in love with a floor plan: what does zero down actually buy at this price point for your household size, versus a conventional or FHA path on an existing home elsewhere in Red Lion's borough, where public sewer runs through the Red Lion Municipal Authority's system into the Mill Creek interceptor shared with York Township, Dallastown, and Windsor Township. Location determines your available financing paths as much as it determines your commute or your school district, and in Red Lion right now, the line between one and the other can run through the middle of a single zip code.
A Related Quirk Worth Knowing
If you've received mail addressed to Red Lion and assumed that settles which municipality you're actually in, it's worth double-checking. The Red Lion post office handles mail for the borough itself as well as parts of Windsor Township and York Township, and your tax bill, not your envelope, is what tells you which one applies. It's the same category of mismatch that puts Hudson Ridge's Red Lion address inside the Dallastown school district, and it's exactly the kind of detail a spreadsheet of listings won't flag for you.
Frequently Asked Questions
Does a USDA-eligible label mean the home is missing typical amenities? No. USDA loans can finance new construction with standard finishes, HOA communities, and modern floor plans. Eligibility is about the property's location and the borrower's income, not the home's features.
What if my income is above the USDA ceiling? Conventional and FHA financing remain available throughout Red Lion, including inside the borough and in the surrounding townships, and a local lender can walk through which structure fits your situation.
Do USDA boundaries and income limits change? Yes. Both the eligible-area map and the income tables are reviewed and updated, most recently with a new federal income table effective July 13, 2026. A property or household that didn't qualify last year may qualify now, or vice versa.
If you're weighing a new build at Hudson Ridge against an existing home elsewhere in Red Lion, the right first step isn't picking a floor plan. It's finding out which financing paths actually apply to your household and the specific address you're considering. Nick Bostic works Red Lion and the surrounding York County market daily and can walk through what's actually available for your situation. Reach out to schedule a consultation or browse the Red Lion neighborhood guide to see what's currently on the market.
This article is general information, not legal, tax or financial advice. Consult a qualified professional about your situation.